---
title: Commodity Prices Remind Us Why We’re Allergic to Leverage
description: One major impact from Russia’s invasion of Ukraine has been to pour fuel on the fire of rising commodities. And, as we are often reminded during crises, it’s difficult to see around every corner, and predict corollary impacts from resulting volatility.
image: https://blog.longshortadvisors.com/hubfs/prospector.png
---
[](https://longshortadvisors.wpcomstaging.com/)
[Subscribe for Updates ](https://blog.longshortadvisors.com/news-insights/commodity-prices-remind-us-why-were-allergic-to-leverage#subscribe)
#### Subscribe for Updates
Receive the latest News & Insights from Long Short Advisors.
[Long Short Advisors Don't Time The Market – Invest In It ](https://longshortadvisors.wpcomstaging.com/)
[March 17, 2022](https://blog.longshortadvisors.com/news-insights/commodity-prices-remind-us-why-were-allergic-to-leverage)
One major impact from Russia’s invasion of Ukraine has been to pour fuel on the fire of rising commodities. And, as we are often reminded during crises, it’s difficult to see around every corner, and predict corollary impacts from resulting volatility.
##### History Rhymes
Bad things rarely happen in isolation. There are knock-on effects that we can’t see in advance.
The Russian financial crisis in 1998 caused the collapse of Long Term Capital Management. The unwinding of the housing bubble led to the demise of Lehman, Bear Stearns, et al. When these types of events happen, it is a reminder as to why we often state that we are “leverage allergic.”
Let’s look at an example in the current market and let’s start with commodity prices.
##### Commodity Prices Hitting All-Time Highs
The price of Gold rallied above $2,000 an ounce. Crude Oil jumped over $130 a barrel, reaching its highest since July 2008. Oil prices are at their highest level in a decade. European Natural Gas prices skyrocketed 80% and shattered records for the biggest weekly rise ever in history.
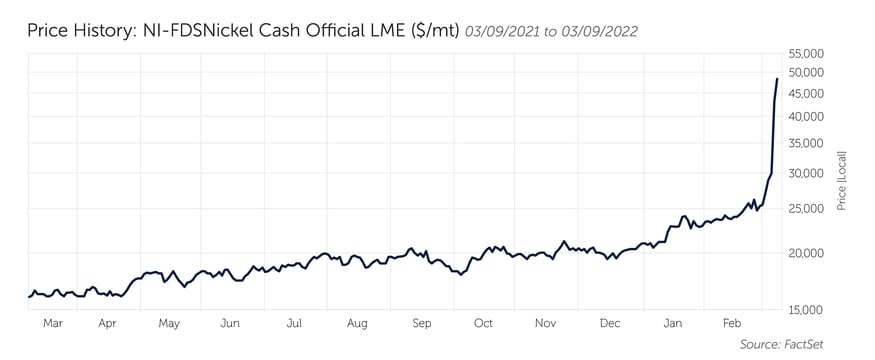
Nickel prices more than doubled to post its second-biggest intra-day gain ever.
##### Why is a value investor writing about commodity prices and nickel?
Because leverage on the balance sheet of a company could be dangerous. Companies in the commodities space can be highly levered. They are also subject to macro dynamics such as commodity price fluctuation. The combination can be devastating.
Reports are that the recent spike in nickel prices is due to a Chinese steel producer being caught short a large amount of nickel and forced to cover. Whether this is true remains to be seen, but it serves as a reminder that leverage can often be dangerous — especially in a time of crisis. After all, as one of our favorite sayings goes… ”To finish first, you must first finish.”
14658192-UFD-03142022
Source: [Prospector Partners](https://blog.prospectorpartners.com/commodity-prices-remind-us-why-were-allergic-to-leverage?utm_campaign=Prospector%20Partners%20Blog&utm_medium=email&_hsmi=206446149&_hsenc=p2ANqtz-8xTcpnkU5Vg9-s4j_RXoF3QtPGDOARwQnbfKkB9DlIMsv5TbqAhHfs4IqhGBZ9F9guOs_ub6zqO4gvot5kjhek78gce0e-9vHjfP3inDvlWgJEenE&utm_content=206446149&utm_source=hs_email)
##### Recent News & Insights
[ ](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
###### [LSOFX Q3 2025 Shareholder Letter](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
[October 24, 2025](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
[ ](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
###### [Portfolio Manager Insights: Bank M&A Could Be Poised For a Comeback](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
[August 28, 2025](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
[ ](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
###### [LSOFX Q2 2025 Shareholder Letter](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
[July 16, 2025](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
##### LSOFX Quick Links
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/db6299b5-cf49-40b0-9862-bd99dc7be4c6)
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/2053dcc5-4dde-46af-aebf-e389c1c850a7)
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/84103a14-2fa1-486e-b359-15bcceacebf6)
### SUBSCRIBE FOR UPDATES
3330 Fairchild Gardens Avenue
Suite 30428
Palm Beach Gardens, FL 33410 [info@longshortadvisors.com](mailto:info@longshortadvisors.com) [215.399.9409](tel:2153999409)
### SUBSCRIBE FOR UPDATES
**You should carefully consider the investment objectives, potential risks, management fees, and charges and expenses of the Fund before investing. The Fund's prospectus contains this and other information about the Fund, and should be read carefully before investing. You may obtain a current copy of the Fund's prospectus by calling (877) 336-6763. **
Investment in shares of a long/short equity fund have the potential for significant risk and volatility. A short equity strategy can diminish returns in a rising market as well as having the potential for unlimited losses. These types of funds typically have a high portfolio turnover that could increase transaction costs and cause short-term capital gains to be realized.
The Fund may lose money due to fluctuations within the stock market which may be unrelated to individual issuers and could not have been predicted. The price of the securities which the Fund holds may change unpredictably and due to local, regional, international, or global events. In the case of a general market downturn, multiple asset classes, or the entire market, may be negatively affected for an extended and unknown amount of time.
Past performance is no guarantee of future results. Diversification cannot ensure a profit or protect against loss in a declining market. It is a strategy used to help mitigate risk
Distributed by Ultimus Fund Distributors, LLC. Member [FINRA](https://www.finra.org/#/)
Long Short Advisors is registered as an investment adviser with the Securities and Exchange Commission. There is no affiliation between Ultimus Fund Distributors, LLC, Long Short Advisors, and the other firms referenced on this website.