---
title: Don’t Look to the Income Statement to Gauge Company Health
description: At Prospector we evaluate all of our investments from the perspective of downside risk mitigation above all else. Across all industries, we target companies with strong, low-leverage balance sheets, dependable free cash flow generation, owner-oriented management teams, and M&A potential.
image: https://blog.longshortadvisors.com/hubfs/LSA-CompanyHealth.jpg
---
[](https://longshortadvisors.wpcomstaging.com/)
[Subscribe for Updates ](https://blog.longshortadvisors.com/news-insights/dont-look-to-the-income-statement-to-gauge-company-health#subscribe)
#### Subscribe for Updates
Receive the latest News & Insights from Long Short Advisors.
[Long Short Advisors Don't Time The Market – Invest In It ](https://longshortadvisors.wpcomstaging.com/)
[July 17, 2023](https://blog.longshortadvisors.com/news-insights/dont-look-to-the-income-statement-to-gauge-company-health)
*Insights from Prospector Partners, Sub Advisor to the LS Opportunity Fund.*
At Prospector, when we evaluate a company our first objective is to assess its downside risk. We do this by looking at the balance sheet first, followed by the cash flow statement, and finally the income statement. This is the inverse of how most equity analysts approach fundamental analysis and how management teams typically discuss their financials on quarterly earnings calls. The income statement is of the least importance to us simply because it’s the easiest financial statement to manipulate and, for a variety of reasons, company executives do not hesitate to make substantial adjustments to their earnings in order to paint the rosiest possible picture for investors.
##### *“When we evaluate a company our first objective is to assess its downside risk. We do this by looking at the balance sheet first, followed by the cash flow statement, and finally the income statement.”*
##### Record Level of Earnings Adjustments in 2022
A [recent study](https://www.wsj.com/articles/earnings-adjustments-topped-an-average-of-1-billion-for-big-companies-last-year-aeebaed2) conducted by research firm Calcbench, which looked at the earnings from 200 S&P 500 companies in 2022, revealed that on average, non-GAAP net income exceeded the corresponding GAAP figure by $1.1 billion. The adjustments represented an impressive 38% of GAAP net income, up from 14% in 2021. Of the companies that reported non-GAAP earnings, 83% adjusted their net income upward.
##### Non-GAAP Earnings: An Unreliable Indicator of Company Health
Now faced with increasing scrutiny from the SEC, management teams argue that adjusted earnings figures represent the performance of their company’s “core” operations, helping investors differentiate the impact of one-off events from the performance of the underlying business. While this is true to an extent, companies have become dependent on these tactics in order to shine a positive light on their business. We think prudent investors should avoid relying too heavily on non-GAAP earnings as a measure of company health.
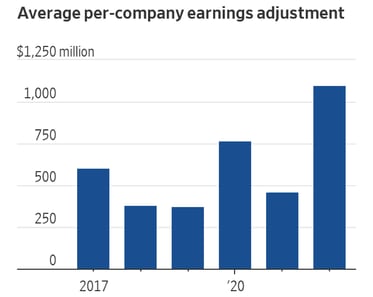
Source: [Calcbench](https://www.wsj.com/articles/earnings-adjustments-topped-an-average-of-1-billion-for-big-companies-last-year-aeebaed2)
Academic studies have indicated that adjustments to the income statement are more frequent and larger when economic conditions are deteriorating. It’s also notable that executive compensation packages are commonly determined by non-GAAP financial measures. In a [2022 publication](https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3030953&mod=article_inline) from MIT’s Robert Pozen, it was shown that firms reporting the largest difference between GAAP and adjusted earnings awarded higher pay packages to their CEOs and were more likely to beat the earnings targets specified in their compensation plans.
##### *“Academic studies have indicated that adjustments to the income statement are more frequent and larger when economic conditions are deteriorating.” *
Alas, the obvious conflicts of interest surrounding income statement adjustments do not prevent many investors from basing their investment decisions around simplistic metrics like the P/E ratio, which we pay relatively less attention to. Deep fundamental analysis remains at the heart of our practice, and that means rolling up our sleeves to identify companies with resilient balance sheets, strong free cash flow generation, and management teams that act in the best interest of their shareholders. Our approach to equity analysis, which resembles the way fixed income analysts approach credit investing, involves scrupulous financial modeling, regulatory and statutory financial statement decomposition, and direct conversations with the company. We believe our steadfast focus on downside risk mitigation will continue to produce superior risk-adjusted returns across market cycles.
Source: [Prospector Partners](https://blog.prospectorpartners.com/dont-look-to-the-income-statement-to-gauge-company-health?utm_campaign=Prospector%20Partners%20Blog&utm_medium=email&_hsmi=264644571&_hsenc=p2ANqtz--oSSrLzh8FeS3EanEB9J9UFcdp9UAHw10qlI_sgboK1P3TbAfwOfyygGFdposkOnPJ6wSW2aKRzltsLslM9GGz0Gjz0z1Wn9tRIXlZgrugkWN0oe4&utm_content=264644571&utm_source=hs_email)
17095985-UFD-07052023
##### Recent News & Insights
[ ](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
###### [LSOFX Q3 2025 Shareholder Letter](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
[October 24, 2025](https://blog.longshortadvisors.com/news-insights/lsofx-q3-2025-shareholder-letter)
[ ](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
###### [Portfolio Manager Insights: Bank M&A Could Be Poised For a Comeback](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
[August 28, 2025](https://blog.longshortadvisors.com/news-insights/bank-ma-could-be-poised-for-a-comeback)
[ ](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
###### [LSOFX Q2 2025 Shareholder Letter](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
[July 16, 2025](https://blog.longshortadvisors.com/news-insights/lsofx-q2-2025-shareholder-letter)
##### LSOFX Quick Links
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/db6299b5-cf49-40b0-9862-bd99dc7be4c6)
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/2053dcc5-4dde-46af-aebf-e389c1c850a7)
[](https://cta-redirect.hubspot.com/cta/redirect/4808633/84103a14-2fa1-486e-b359-15bcceacebf6)
### SUBSCRIBE FOR UPDATES
3330 Fairchild Gardens Avenue
Suite 30428
Palm Beach Gardens, FL 33410 [info@longshortadvisors.com](mailto:info@longshortadvisors.com) [215.399.9409](tel:2153999409)
### SUBSCRIBE FOR UPDATES
**You should carefully consider the investment objectives, potential risks, management fees, and charges and expenses of the Fund before investing. The Fund's prospectus contains this and other information about the Fund, and should be read carefully before investing. You may obtain a current copy of the Fund's prospectus by calling (877) 336-6763. **
Investment in shares of a long/short equity fund have the potential for significant risk and volatility. A short equity strategy can diminish returns in a rising market as well as having the potential for unlimited losses. These types of funds typically have a high portfolio turnover that could increase transaction costs and cause short-term capital gains to be realized.
The Fund may lose money due to fluctuations within the stock market which may be unrelated to individual issuers and could not have been predicted. The price of the securities which the Fund holds may change unpredictably and due to local, regional, international, or global events. In the case of a general market downturn, multiple asset classes, or the entire market, may be negatively affected for an extended and unknown amount of time.
Past performance is no guarantee of future results. Diversification cannot ensure a profit or protect against loss in a declining market. It is a strategy used to help mitigate risk
Distributed by Ultimus Fund Distributors, LLC. Member [FINRA](https://www.finra.org/#/)
Long Short Advisors is registered as an investment adviser with the Securities and Exchange Commission. There is no affiliation between Ultimus Fund Distributors, LLC, Long Short Advisors, and the other firms referenced on this website.